Call Us Today 630-780-1034

- Home
- Team
- Estate Planning
- Comprehensive, Risk-Managed Estate Planning
- The Risks Most Families Never See Coming
- Why Traditional Estate Planning Often Falls Short
- Living Trust and Probate Avoidance
- Wills Vs. Trusts
- Special Needs Trusts
- Trust Funding
- Inheritance and Beneficiary Planning
- Divorce & Creditor Protection for Children
- High Net Worth Estate Planning
- Family Transitions & Wealth Preservation
- Estate Tax Planning
- Protection Planning for Minor Children
- Protecting an Inheritance for a Vulnerable Beneficiary
- Family Protection and Incapacity Planning
- Planning for Long-Term Care and Health Risks
- Retirement and Estate Planning for Seniors
- Planning for Blended & Non-Traditional Families
- Protecting Children's Inheritances
- Blended Family Estate Planning for Seniors
- Estate Planning for Second Marriages
- Estate Planning for Stepchildren
- Protecting Children While Providing for a Spouse
- Estate Planning for Estranged Children
- Estate Planning for Sibling Conflict
- Estate Planning for Families with Complicated Relationships
- Family Wealth Preservation & Estate Tax Planning
- Transfer on Death Instruments
- Protecting Your Legacy: Lawsuit, Creditor, Divorce, and Long-Term Care Protection
- Asset Protection & Professional Planning
- How Gateville Law Firm is Different
- Probate & Estate Administration
- Comprehensive, Risk-Managed Estate Planning
- Trust Administration
- Family Law
- Media
- Testimonials
- Videos
- News
- Estate Planning Resources
- Estate Planning 101: How to Protect Your Family, Home, and Assets in Illinois
- Set it and Forget it: Why Updating Your Estate Plan Is One of the Most Important Things You Can Do
- The Risk of Beneficiary Designations and Payable on Death Accounts in Illinois
- What Happens if I Die Without a Will or Trust in Illinois?
- What Is Probate?
- What Is the Difference Between a Will and a Living Trust in Illinois?
- Events
- Blog
- Contact
Plano Medicaid Asset Protection Trust Lawyers
- A Medicaid Asset Protection Trust is an irrevocable trust that can hold selected assets that will be managed by a trustee for named beneficiaries. The person who creates the trust will usually give up direct ownership of and access to the principal.
- A MAPT does not guarantee eligibility for Medicaid, and it is not a shortcut to benefits. Whether it may be used will depend on a family's health, income, assets, and goals.
- Transfers made during the 60 months before a Medicaid long-term care application will be reviewed. Transfers for less than fair market value may trigger a penalty period.
- Homes, rental properties, investments, CDs, bank accounts, and retirement accounts can each raise different legal, tax, and practical questions. Listing an asset for review does not mean it should go into a trust.
- For 2026, Illinois allows a community spouse to keep up to $143,172 in non-exempt resources, plus the home, a car, and household furnishings. A separate income allowance of up to $4,066.50 per month will also apply.
- An irrevocable trust will affect control, access, taxes, financing, and property management. Losing direct access to assets can be a serious consideration for a family.
- A revocable living trust can be changed, and it does not protect assets from Medicaid, while a MAPT cannot easily be changed. Some families may use both types of trusts.
Attorneys Helping Families Plan Ahead for Long-Term Care in Plano, IL
If you own a home, have savings or investments, or want to leave assets to your family, the possibility that you may need long-term care can raise difficult questions. Will your spouse be able to remain at home? How will care be paid for? Could your home, rental property, certificate of deposit, or investment account be part of your plan?
A Medicaid Asset Protection Trust (MAPT) is one planning tool to consider before care is needed. It is generally irrevocable, and it may involve giving up direct access to certain assets. It will not guarantee eligibility for Medicaid, and whether it may be used as part of your estate plan will depend on your health, income, family, assets, and goals. At Gateville Law Firm, our lawyers can help you understand the issues you may need to address and evaluate the possible next steps as you plan for long-term care.
Need an Estate Plan?
Call Gateville Law Firm at 630-780-1034 to schedule your consultation and protect your family's future with confidence.
Who May Want to Explore a MAPT
A MAPT may be worth discussing with pre-retirees, retirees, older adults, couples, and families who are helping a parent plan for the possibility of nursing-home care or other forms of long-term care. It may be particularly relevant when a family owns a home or other real estate property, has accumulated savings or investments, wants to protect a spouse who may remain at home, or hopes to pass some assets to children or other beneficiaries.
There is no single age, asset amount, or family situation that makes a MAPT right for everyone. Planning should consider both possibilities: care may be needed sooner than expected, or it may never be needed. It should also preserve enough flexibility and liquidity for ordinary living expenses, health needs, emergencies, property costs, and other goals.
What a Medicaid Asset Protection Trust Does
A MAPT is generally an irrevocable trust that is created under written terms. The person creating the trust will transfer selected assets to it, and a trustee will manage those assets for the beneficiaries identified in the document. The person who creates the trust typically gives up direct ownership of, and unrestricted access to, the principal transferred into the trust. The exact consequences will depend on the trust language, the assets, who may receive distributions, and the family's circumstances.
When addressing Medicaid long-term-care benefits, Illinois officials will review certain transfers made during the 60 months before an application. A transfer for less than the fair market value of an asset may result in a penalty period that could delay Medicaid long-term-care coverage, depending on the facts and any applicable exceptions. A transfer to a trust does not make the transfer disappear from that review. The timing of transfers, the terms of a trust, the applicant's circumstances, and current program rules will all play a role in determining eligibility.
A MAPT is not a shortcut to benefits, a guarantee that property will be treated a particular way, or a promise that all expenses related to long-term care will be covered. An estate plan should be considered alongside care options, financial resources, tax issues, and the needs of the people who depend on those resources.
Assets Families in Plano May Want to Review
A useful planning conversation will look at a family's full financial picture. Depending on the family, that may include:
- A Primary Residence: Who owns a home, who lives there, whether there is a mortgage, the home's equity, and whether the owner may want to sell, move, or have a spouse continue living there should all be considered.
- Rental or Investment Properties: The titles, co-owners, debts, rental income, repairs, insurance, taxes, property management, and plans for future sales or transfers of these properties may be factors to review.
- Non-Retirement Investments: A plan may consider brokerage accounts, stocks, bonds, mutual funds, and other investments, including income, taxes, access, and market risk.
- Certificates of Deposit and Bank Accounts: Issues such as ownership, maturity dates, early-withdrawal terms, liquidity, and the need to pay for care or household expenses may play a role in decisions.
- Retirement Accounts, Life Insurance, Income, and Jointly Owned Assets: These may follow different rules, and each asset should be reviewed individually, including beneficiary designations and the effects on a spouse.
Listing an asset for review does not mean it should be transferred to a trust. A home and a CD will raise different questions. Rental property may generate income that a family needs. Investment accounts may be important for living expenses. Retirement accounts have separate tax and distribution rules. Each asset should be evaluated to address its legal treatment, practical use, tax consequences, and role in the family's plan.
Why the Medicaid Five-Year Look-Back Makes Timing Important
When someone applies for Illinois Medicaid long-term care coverage, the state may review transfers made during the 60 months before the application. This is commonly called the five-year look-back. Gifts that were made during this period will not automatically disqualify an applicant. However, a transfer for less than fair market value may result in a penalty period, which can leave a family responsible for long-term care costs during the period when Medicaid will not pay for covered services.
Starting early can give a family more time to understand the consequences of a transfer, compare alternatives, and coordinate a plan with the person's spouse and intended beneficiaries. Waiting until a hospitalization, nursing home placement, or application deadline can make decisions more urgent. A MAPT will not erase the look-back period, and five years passing after establishing a trust will not guarantee eligibility. Before giving away money, adding someone to a deed, retitling an account, or funding a trust, it is important to receive legal advice based on a family's full situation.
"The whole team at Gateville Law was extremely helpful, kind, and knowledgeable. They answered all of our questions and helped us make the best decisions for our family and estate planning. We are very happy with all the help they provided."
Protecting a Spouse Who Remains at Home
When one spouse needs long-term care, planning must also account for the health, housing, income, and financial stability of their spouse. The couple's resources, income, household expenses, ownership arrangements, and care needs will all need to be considered. Medicaid has rules addressing spouses, but applying them to a particular family will require a current review of the facts and the requirements of the program.
A plan should not assume that a spouse who continues to live at home will be able to manage indefinitely without access to funds or decision-making authority. Powers of attorney, account ownership, the home, income sources, and the couple's estate plan may all need to be reviewed. A MAPT may or may not be appropriate; it is only one possible part of the analysis.
What Can the Community Spouse Keep?
Illinois has special rules that are followed when one spouse applies for Medicaid long-term benefits, and the other spouse will continue living in the community. For applications received on or after January 1, 2026, Illinois has set the Community Spouse Resource Allowance (CSRA) at up to $143,172 in non-exempt resources. This is the state's 2026 standard, and the actual amount that may be available to transfer will depend on the resource assessment and the community spouse's existing non-exempt resources. The allowance is not a limit on everything the community spouse may own.
For example, if the community spouse already has $40,000 in non-exempt resources, the basic CSRA calculation may leave up to $103,172 to transfer to that spouse or for the spouse's sole benefit, subject to the eligibility rules and the facts of a case. A court order or appeal may allow for a higher amount in certain circumstances. Because asset treatment, ownership, and timing can affect a case, this example is only an illustration, not an actual eligibility determination.
The community spouse may retain the couple's home, a car, and household furnishings. These are considered separately from the CSRA, although the home's treatment can depend on the facts and the particular Medicaid program used. Countable resources may include cash, bank accounts, certificates of deposit, stocks, investments, retirement resources, and interests in other real estate property. The exact treatment of an asset can depend on who owns it, how it is structured, and whether a specific exclusion applies.
There is not a simple list of assets that a community spouse is forbidden to own. Instead, the non-exempt resources of both spouses will be reviewed under the long-term-care rules. Resources above the applicable allowance may be treated as available to pay for the spouse's care. Separate eligibility rules will apply to the spouse applying for benefits, and transferring assets for less than fair market value can create a look-back penalty. Do not give away, retitle, or move property to try to fit under an allowance without receiving legal advice.
The CSRA concerns assets, not monthly income. Illinois has also established a separate 2026 Community Spouse Maintenance Needs Allowance of up to $4,066.50 per month. That income standard will generally be reduced by the community spouse's own gross income when determining whether income may be diverted from the spouse receiving long-term care. It is not a ceiling on the community spouse's own income.
Understand the Tradeoffs Before Transferring Property
An irrevocable trust can affect who controls property and how readily a family can use it. Before transferring assets, it is important to consider who will serve as trustee, what authority the trustee will have, whether the grantor can receive income, how property expenses will be paid, and what will happen if the home or rental property needs to be sold, refinanced, repaired, or no longer suits the family.
The plan may also affect taxes, financing, insurance, rental management, capital gains, and inheritance goals. If an asset is difficult to replace, or if a family may need it to pay for care, losing direct access can be a serious tradeoff. An attorney can explain the legal structure and identify tax or financial questions that may require input from the family's tax professional or financial adviser.
Should a Family Use a MAPT or Revocable Living Trust?
A revocable living trust can be used to organize assets and make sure they will be managed correctly during a person's incapacity and distributed after their death. The person who creates a living trust will generally retain the ability to change or revoke it. A MAPT has a different purpose, and it is irrevocable, with different consequences for ownership, control, and access. One trust should not be treated as a substitute for the other. Some families may use both types of trusts as part of a coordinated estate plan, but the documents and asset titles must work together.
Questions to Ask Before Choosing a Plan
- What care settings may be relevant, and what costs might a family need to address?
- How much income and liquid savings should remain available for a person and their spouse?
- What assets have been transferred or retitled during the past five years?
- Who will manage a home, rental property, or investments if the owner can no longer do so?
- Will a family be comfortable giving up direct access to principal placed in an irrevocable trust?
- How should the plan coordinate with powers of attorney, wills, revocable trusts, and beneficiary designations?
For an initial review, it is important to gather existing estate-planning documents, deeds, account statements, income information, insurance details, and a list of gifts or ownership changes during the past five years. This can help an attorney identify the questions that will need to be answered before a family makes a transfer or applies for benefits.
Frequently Asked Questions About Medicaid Asset Protection Trusts
In many cases, yes. A MAPT can be written to give the person who created it the right to live in the home for the rest of their life. However, the trust terms must be drafted carefully, and the family will need a clear plan for paying property taxes, insurance, utilities, and repairs.
Some MAPTs allow the person who created the trust to receive income generated by trust assets, such as interest, dividends, or net rental income. The principal itself is usually not available to that person. Any income paid out may still count as income when Medicaid reviews eligibility, so the terms of the trust should match the family's actual budget and long-term goals.
If someone applies for Medicaid long-term care coverage within 60 months of funding a MAPT, the transfer will generally be reviewed under the look-back rules. A penalty period may apply, and the family may need to pay for care privately during that time. Assets that remain outside the trust, long-term care insurance, and other strategies may help bridge that gap.
Because a MAPT is irrevocable, the person who created it generally cannot cancel it or take assets back. Some trusts may include limited flexibility, such as the power to change terms related to which family members will eventually receive trust property. Any change should be reviewed carefully, since it could affect Medicaid eligibility or taxes.
No. Medicaid may also help pay for certain home-based and community-based services, and the rules for these programs can differ from the rules for nursing home care. A plan that considers several possible care settings can give a family more options.
Contact Our Plano, Illinois Long-Term Care Planning Attorneys
Gateville Law Firm is based in Yorkville, and we serve individuals and families in Plano and other nearby communities. We help clients understand how a possible need for long-term care may affect a home, savings, investments, a spouse, and plans for the next generation. Our role is to explain the available choices, discuss the limits and tradeoffs of each strategy, and help a family make informed decisions based on their circumstances.
If you are considering a Medicaid Asset Protection Trust, you can start with a review of your goals, assets, timing, and concerns about long-term care. If a person may need care in the near future, seek advice promptly before giving away assets, changing title, closing accounts, or signing financial paperwork. Contact our Plano, IL Medicaid asset protection trust lawyers at 630-780-1034 to request a consultation.
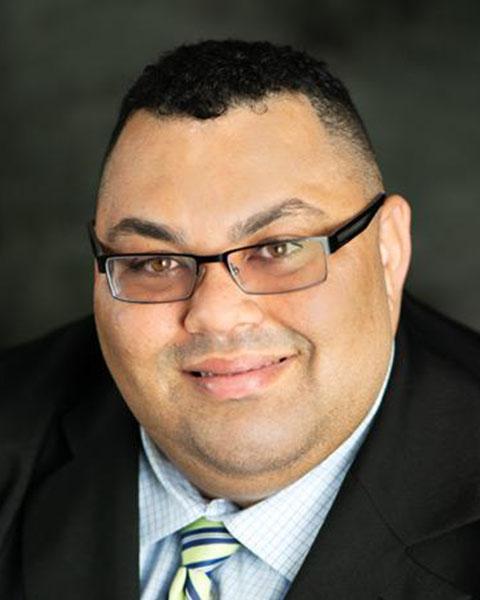
Sean Robertson
Visit Attorney ProfileSean Robertson has more than 21 years of legal experience helping individuals, families, business owners, and investors protect their assets and plan for the future. As the Founding Partner of Gateville Law Firm, he provides guidance in estate planning, tax planning, business planning, and asset protection.
- 21+ years serving estate planning and business planning clients
- Licensed to practice law in Illinois since 2003
- Graduate of DePaul University College of Law
- Founding Partner of Gateville Law Firm
- Estate Planning Faculty Presenter for the National Business Institute
- Recipient of multiple professional recognitions including Best of the Fox and Elite Lawyer

Gateville Law Firm
provides excellent estate
planning service.

"Sean's team is knowledgeable, responsive, and dedicated to ensuring clients feel confident in their decisions. Sean & Connie take the time to answer questions thoroughly, making complex legal matters easy to understand."
In Service of Your Wealth
If you own assets with a value in excess of $1 million, it is crucial to take steps to ensure that your wealth will be preserved and passed on to future generations. Failure to do so could lead to financial losses due to lawsuits, actions by creditors, or other issues. You will also need to be aware of potential estate taxes that may apply at both the state and federal levels. When working with our attorneys, you can make sure your wealth will be properly preserved.
Our estate planning team can provide guidance on the best asset protection options that are available to you. With our help, you can reduce the value of your taxable estate to ensure that more of your wealth will be preserved for future generations. We can also help you use asset protection trusts or other methods to make sure your property will be safeguarded. Our goal is to provide you with assurance that your family will be prepared for whatever the future may bring.
Blog
Who Will Pay for Long-Term Care? What Families Should Understand Before a Crisis
Posted on October 29, 2026 in Estate Planning
How Illinois Medicaid’s Five-Year Look-Back Can Affect Long-Term Care Planning
Posted on October 23, 2026 in Estate Planning
Illinois Estate Tax Planning: Portability, Family Trusts and Protecting Children’s Inheritance
Posted on October 20, 2026 in Estate Tax Planning
|
Yorkville Office520 E Kendall Drive, Suite C |
Sign Up for
Our Seminar
From our office in Yorkville, we provide services to clients throughout Kendall County, Kane County, DeKalb County, LaSalle County, Grundy County, and the surrounding areas, including Aurora, Big Rock, Boulder Hill, Newark, Ottawa, Joliet, Leland, Morris, LaSalle, Minooka, Montgomery, Plainfield, Plano, Oswego, Sandwich, Somonauk, Sugar Grove, Mendota, Earlville, Serena, Sheridan, Marseilles, Lisbon, and Plattville.
Results listed are not a guarantee or indication of future case results.


520 E Kendall Drive, Suite C
Yorkville, IL 60560
630-780-1034


